Guide treatment: Reference. Essential guidance is in the page content below.
Bitcoin Risk and Security
Bitcoin Insurance Is Not the Same as Bitcoin Security
Bitcoin insurance can provide meaningful financial protection against specific covered events. It does not guarantee that lost Bitcoin will be replaced in full, and it does not prevent the loss from happening.
Policy limits, exclusions, deductibles, valuation rules and claims procedures all matter. More importantly, insurance should sit behind a resilient Bitcoin security architecture, not replace one.
Insurance structures vary materially across providers, insurers, jurisdictions and customer types. Coverage is governed by the applicable policy wording and customer-specific insurance schedule, not by a provider’s headline coverage amount.
What Bitcoin Insurance Actually Is
Bitcoin insurance is a contract under which an insurer agrees to compensate an insured party for specified losses, subject to the policy’s terms.
It does not insure “Bitcoin” in the abstract. It insures defined interests, assets, custody arrangements or operational risks up to an agreed limit.
Insurance may apply to:
- a custody provider;
- an individual customer;
- a specific vault;
- an institution;
- a shared custody programme;
- a defined class of operational or physical risks.
Risks Available for Insurance in the Market
Depending on the product, jurisdiction and approved custody arrangement, Bitcoin custody insurance may cover specified events such as:
Institutional fraud or collusion
Dishonest conduct involving employees, operators, custodians or institutional keyholders.
Key compromise
Unauthorised access to signing material held within the approved custody structure.
Theft or burglary
Physical or digital theft occurring under circumstances defined by the policy.
Negligence or operational failure
Specified failures in custody processes, controls, systems or authorised operations.
Fire, flood or catastrophe
Damage or destruction affecting approved key-storage infrastructure or locations.
Cyber events
Some policies may cover defined cyber incidents affecting custody infrastructure, subject to exclusions and security requirements.
Physical coercion: certain specialist policies may cover losses involving kidnapping, extortion or coercion. Do not assume this sits inside every custody policy.
The presence of a risk in a marketing summary does not mean every loss involving that risk will be covered. The policy may require approved devices, named locations, specific custody procedures and evidence that all security obligations were followed.
The Headline Limit Is Not the Whole Policy
Bitcoin insurance does not automatically guarantee:
- full coverage of the customer’s Bitcoin balance;
- a dedicated limit for each customer;
- payment in Bitcoin;
- automatic adjustment when Bitcoin appreciates;
- protection against every form of theft or compromise;
- coverage for provider insolvency;
- coverage for government seizure or account freezing;
- coverage for authorised transactions;
- coverage when required security procedures were not followed;
- no deductible;
- no exclusions;
- immediate payment;
- protection beyond aggregate programme limits;
- a direct legal right for the customer to claim from the insurer.
Why Insurance Becomes Important When Institutions Hold the Keys
Multi-institution custody distributes signing authority across professional organisations. This can materially reduce dependence on any one custodian.
The owner, however, normally does not hold a signing key.
The customer therefore depends on:
- institutional personnel;
- internal controls;
- identity-verification procedures;
- transaction-authorisation workflows;
- custody technology;
- the continuing operation of the participating organisations;
- coordination between institutional keyholders.
Insurance may transfer some of the financial consequences if those institutional or human controls fail in a way covered by the policy.
Insurance is a reasonable financial backstop for residual institutional risk. It remains separate from the architecture that determines who can sign and who must be trusted.
A Bitcoin Position Can Outgrow Its Insurance
A Bitcoin position may appreciate faster than a fixed insurance limit.
If 10 BTC is insured under a US$1 million limit and Bitcoin later doubles in price, the policy limit may still remain US$1 million. Unless the limit adjusts automatically or the customer increases it, only half of the position may remain insured.
Increasing the insured limit may also increase the annual premium.
| Position | Initial Bitcoin value | Later Bitcoin value | Insurance limit | Potential uninsured value |
|---|---|---|---|---|
| 10 BTC | US$1 million | US$2 million | US$1 million | US$1 million |
Not every policy uses a fixed limit. Some insurance structures may include dynamic valuation or periodic adjustment mechanisms. The customer should confirm exactly how the insured value responds when Bitcoin’s market price changes.
How Bitcoin Custody Insurance Is Offered
Bitcoin custody insurance is generally offered through one of two broad structures.
Model 1
Customer-selected insurance limit
Under this structure, the customer chooses a defined amount of insurance coverage, usually expressed in a fiat currency such as US dollars.
The annual premium may be calculated using:
- the selected insurance limit;
- the custody configuration;
- the number and identity of keyholders;
- the geographic distribution of signing material;
- the customer’s risk profile;
- the events included in the policy.
Potential advantages
- the customer can select a level of cover appropriate to the position;
- the limit may be dedicated to the customer;
- coverage may be tailored to the custody arrangement;
- the insured amount and premium are more visible.
Potential limitations
- the selected limit may not automatically track Bitcoin’s price;
- the customer may become underinsured if Bitcoin appreciates;
- increasing the limit may increase the annual premium;
- coverage remains subject to deductibles, exclusions and claims procedures;
- the policy may compensate in fiat rather than Bitcoin.
Model 2
Provider-arranged insurance facility
Under this structure, the custody provider arranges a broader insurance facility covering eligible assets, custody arrangements or customers.
The cost may be:
- included within the custody fee;
- reflected indirectly in pricing;
- subject to a standard included limit;
- supplemented by optional additional coverage.
Potential advantages
- no separate insurance application may be required;
- eligible customers receive a baseline level of protection;
- the provider manages the relationship with the insurer;
- the policy may cover institutional fraud, collusion, compromise or operational failure.
Potential limitations
- the advertised facility size may not be dedicated to each customer;
- aggregate or shared programme limits may apply;
- sublimits may apply to particular events;
- multiple claims may compete for the same facility;
- customer-specific coverage may be lower than the headline amount;
- the customer may not be the named insured;
- the customer may not have a direct claim against the insurer;
- valuation and payment terms may be controlled by the programme policy.
Compensation After Loss Versus Prevention Before Loss
Insurance
- applies after a covered event;
- depends on policy wording;
- requires a valid claim;
- may pay in fiat;
- is limited by the insured amount;
- may involve deductibles and exclusions;
- transfers financial consequences to an insurer.
Security architecture
- determines who holds keys;
- determines who can sign;
- determines whether one party can act alone;
- determines whether one key can fail safely;
- determines whether the owner remains a participant;
- aims to prevent one failure from becoming a loss.
Why We Generally Prioritise Architecture Over Insurance
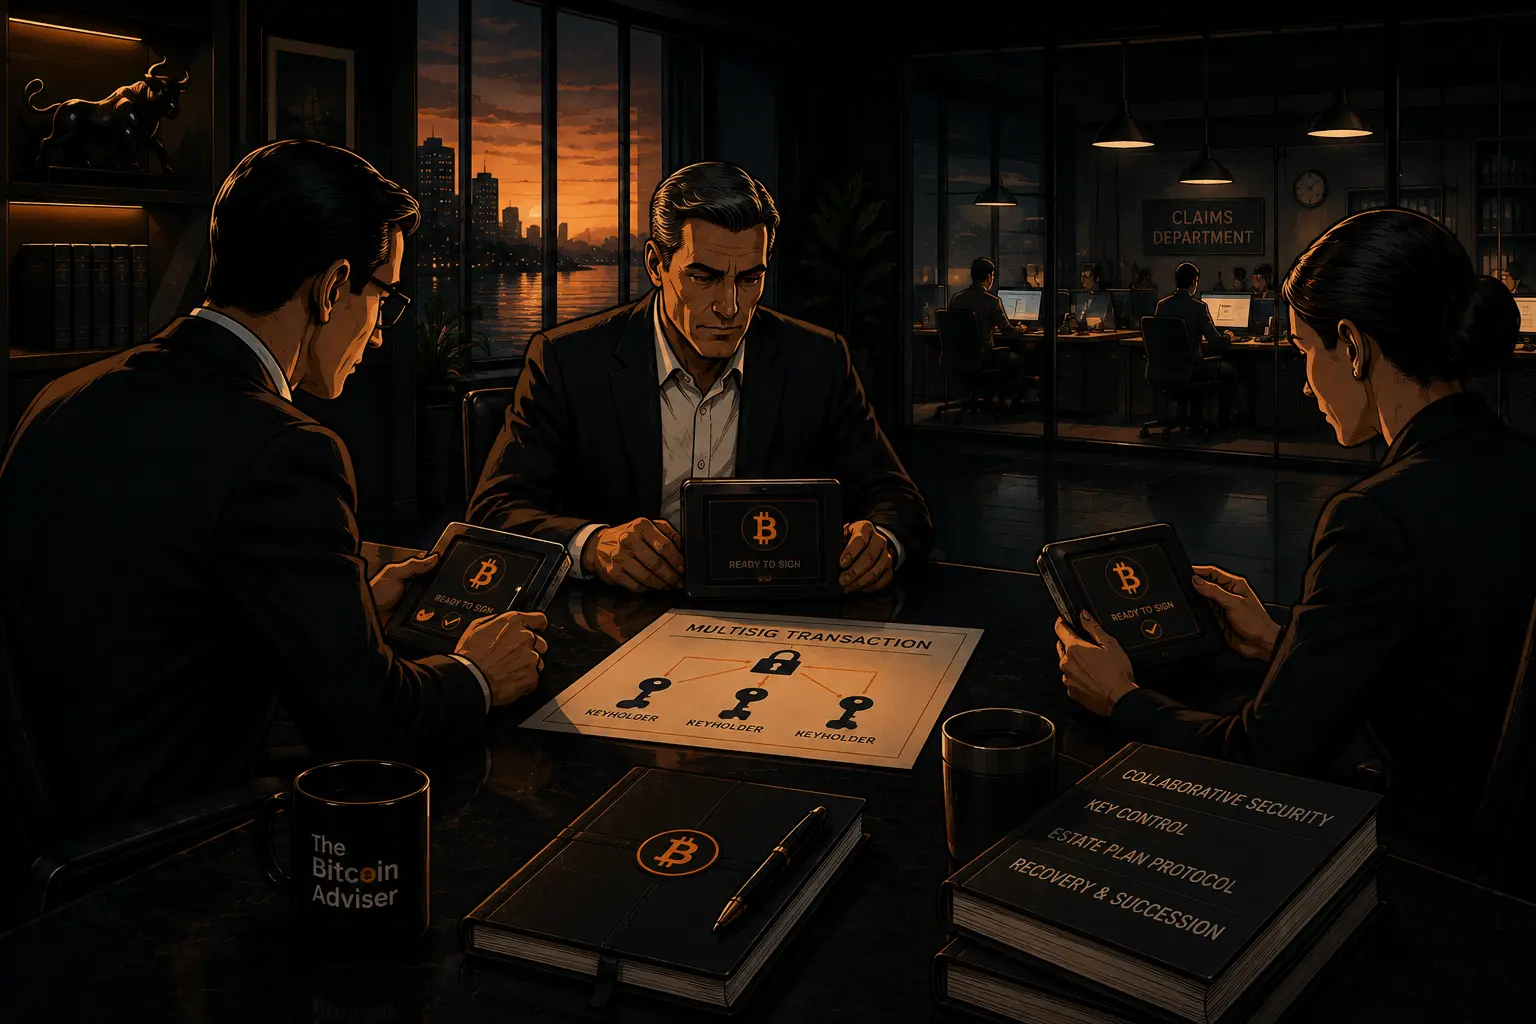
The Bitcoin Adviser uses collaborative security to keep the owner inside the Bitcoin signing structure while distributing professional support, recovery, governance and continuity responsibilities.
The owner holds a key. The professional key agent holds a complementary key. The platform holds a complementary key. No individual party can move the Bitcoin alone.
This means:
- one professional provider cannot unilaterally transact;
- one unavailable key does not necessarily cause loss;
- provider insolvency does not itself transfer the Bitcoin;
- the owner is not relying entirely on institutional authorisation;
- the owner retains direct on-chain visibility;
- recovery and succession can be designed into the structure;
- the failure of one participant should not create a loss requiring an insurance claim.
Many custody insurance products address fraud, collusion, compromise or operational failure involving institutions that hold the customer’s keys.
Collaborative security reduces these risks differently. The owner remains a keyholder, and no professional party has enough signing authority to act alone.
Collaborative security does not eliminate every conceivable risk. Separate insurance may still be relevant for specific physical, personal, cyber or professional risks. Our position is that insurance should sit behind a resilient security architecture, not substitute for one.
Questions to Ask About Any Bitcoin Insurance Arrangement
- Who is the named insured?
- Does the customer have a direct right to make a claim?
- Is the insurance limit dedicated to the customer?
- Is the limit shared across multiple customers?
- Is the limit per customer, per vault, per incident or aggregate?
- Are there event-specific sublimits?
- Is the insured amount denominated in Bitcoin or fiat?
- What price determines the value of Bitcoin at the time of loss?
- Does the limit automatically adjust if Bitcoin appreciates?
- Can the limit be increased during the policy term?
- How does increasing the limit affect the premium?
- Is payment made in Bitcoin or fiat?
- What deductible applies?
- Are employee fraud and institutional collusion covered?
- Are authorised but fraudulent transactions covered?
- Is customer error covered?
- Is provider insolvency covered?
- Is government seizure or freezing covered?
- Are cyberattacks and software defects covered?
- Are physical coercion, kidnapping or extortion covered?
- What security procedures must the customer follow?
- What evidence is required to establish a claim?
- What happens if several customers claim following the same event?
- Which jurisdiction governs the policy and claims process?
- Can the customer review the full policy wording before committing to the custody service?
Where Bitcoin Insurance Fits
| Structure | How protection works | Insurance role |
|---|---|---|
| Owner-managed custody | Owner designs and operates the key architecture | Separate specialist cover may be available for defined personal, physical or cyber risks |
| Single-institution custody | One provider controls the custody environment | Insurance may cover specified theft, compromise, fraud or operational failures |
| Multi-institution custody with selected limit | Signing is distributed across institutions and the customer selects a fiat coverage limit | Coverage can be tailored, but the limit may require adjustment as Bitcoin appreciates |
| Multi-institution custody with programme facility | Signing is distributed across institutions and insurance is arranged across the custody programme | Baseline coverage may be included, but customer limits, aggregate limits and sublimits require confirmation |
| Collaborative security | Owner remains inside distributed signing with professional support | Architecture reduces many provider-failure risks before an insurance claim is needed |
| Bitcoin ETF | Investor owns a financial security rather than Bitcoin directly | Custody insurance operates at fund or service-provider level rather than as direct customer Bitcoin insurance |
Design the Security Architecture Before You Insure the Risk
Before relying on a policy limit, understand who holds the keys, who can sign, what happens if a provider fails, and how your family recovers the Bitcoin.
The Bitcoin Adviser helps individuals, families and institutions build collaborative security structures designed to remain resilient without removing the owner from the signing architecture.