Bitcoin IRA
Take Control: Your IRA, Your Bitcoin, Your Keys, Your Future
As a Bitcoin investor, holding your Bitcoin directly—securely in your own custody—provides the ultimate peace of mind. The Bitcoin Adviser provides technical and operational support for self-custody Bitcoin in IRAs. We are not a financial services company and do not provide financial, tax, legal, or investment advice.
We work alongside trusted partners: Advanta Trust (your IRA custodian) and River (your exchange partner). Together, we help you set up and maintain self-custody Bitcoin in your retirement account while you work directly with your IRA custodian and professional advisors on structure, suitability, and compliance.
For scope, risks, and our alignment with US frameworks, see Scope & Risks and Authority & Standards (US).
Since 2016 Zero satoshis lost
Your Keys You maintain control
All IRA Types Traditional, Roth, SEP, Solo 401(k)
Advanta Trust IRS-authorized custodian
Scott Porter
Self-Directed IRA Technical Specialist · Advanta Trust Collaboration
Scott brings three decades of enterprise IT and security experience to our retirement clients. He provides technical support for the Advanta Trust partnership, coordinating paperwork, compliance documentation, and collaborative security setup. Scott does not provide financial, tax, legal, or investment advice.
Schedule Time with Scott
Bring approximate rollover amounts, target timelines, and existing custodian info. Scott will map next steps and coordinate the technical setup with Advanta Trust and River.
Learn more about Scott's expertise: Visit Scott's page →
Meet The Specialists
Process-led, documentation-first, rehearsed recovery. We work alongside your CPA, attorney, and custodian—we don't replace them.
Do you custody my bitcoin?
No. We provide collaborative security—co-signing under documented authorization and ID verification. You retain control of your keys.
Is this financial or tax advice?
No. We provide education and operational support only. Consult your CPA and attorney for financial, tax, and legal matters.
What does an engagement look like?
Assess → Design → Implement → Maintain. We inventory your situation, design the custody structure, deploy it, and support ongoing reviews.
Retirement Accounts Are Form-Driven
In the US, IRA outcomes are often determined by beneficiary designations and inherited distribution rules—not by what someone "intended" in their will. IRS guidance describes the post-2019 framework where many non-spouse beneficiaries must distribute the account by the end of the 10th year after death, with specific exceptions for eligible designated beneficiaries. We don't provide tax or legal advice; we help you understand the operational and documentation questions to review with your licensed professionals and your IRA provider. See IRS Publication 590-B for inherited IRA rules.
Who This Is For
This page is for U.S.-based Bitcoin holders who want:
- Direct ownership of actual Bitcoin in their IRA (not just ETF exposure)
- A self-directed or rollover IRA with true self-custody of the asset
- Collaborative security and estate planning so retirement Bitcoin can be held for decades and passed on securely
You retain control of your keys. We never act as custodian or take possession of your Bitcoin.
All IRA Types Supported
With the right custodian, Bitcoin can be held in various IRA types. Advanta Trust supports Traditional, Roth, SEP, and Solo 401(k) IRAs. You work directly with Advanta Trust to select and set up your IRA account type and determine whether Bitcoin is appropriate for your situation. The Bitcoin Adviser provides technical support for self-custody once your IRA is established.
Looking for Health Savings Accounts (HSAs)? HSAs offer a unique triple tax advantage and have their own dedicated page. See our Bitcoin HSA page for HSA-specific information, contribution limits, and the triple tax advantage.
Traditional IRA Tax-deferred contributions and growth
Roth IRA Tax-free growth and qualified withdrawals
SEP IRA For self-employed and small businesses
Solo 401(k) For business owners with no employees
How We Simplify Bitcoin IRA Custody
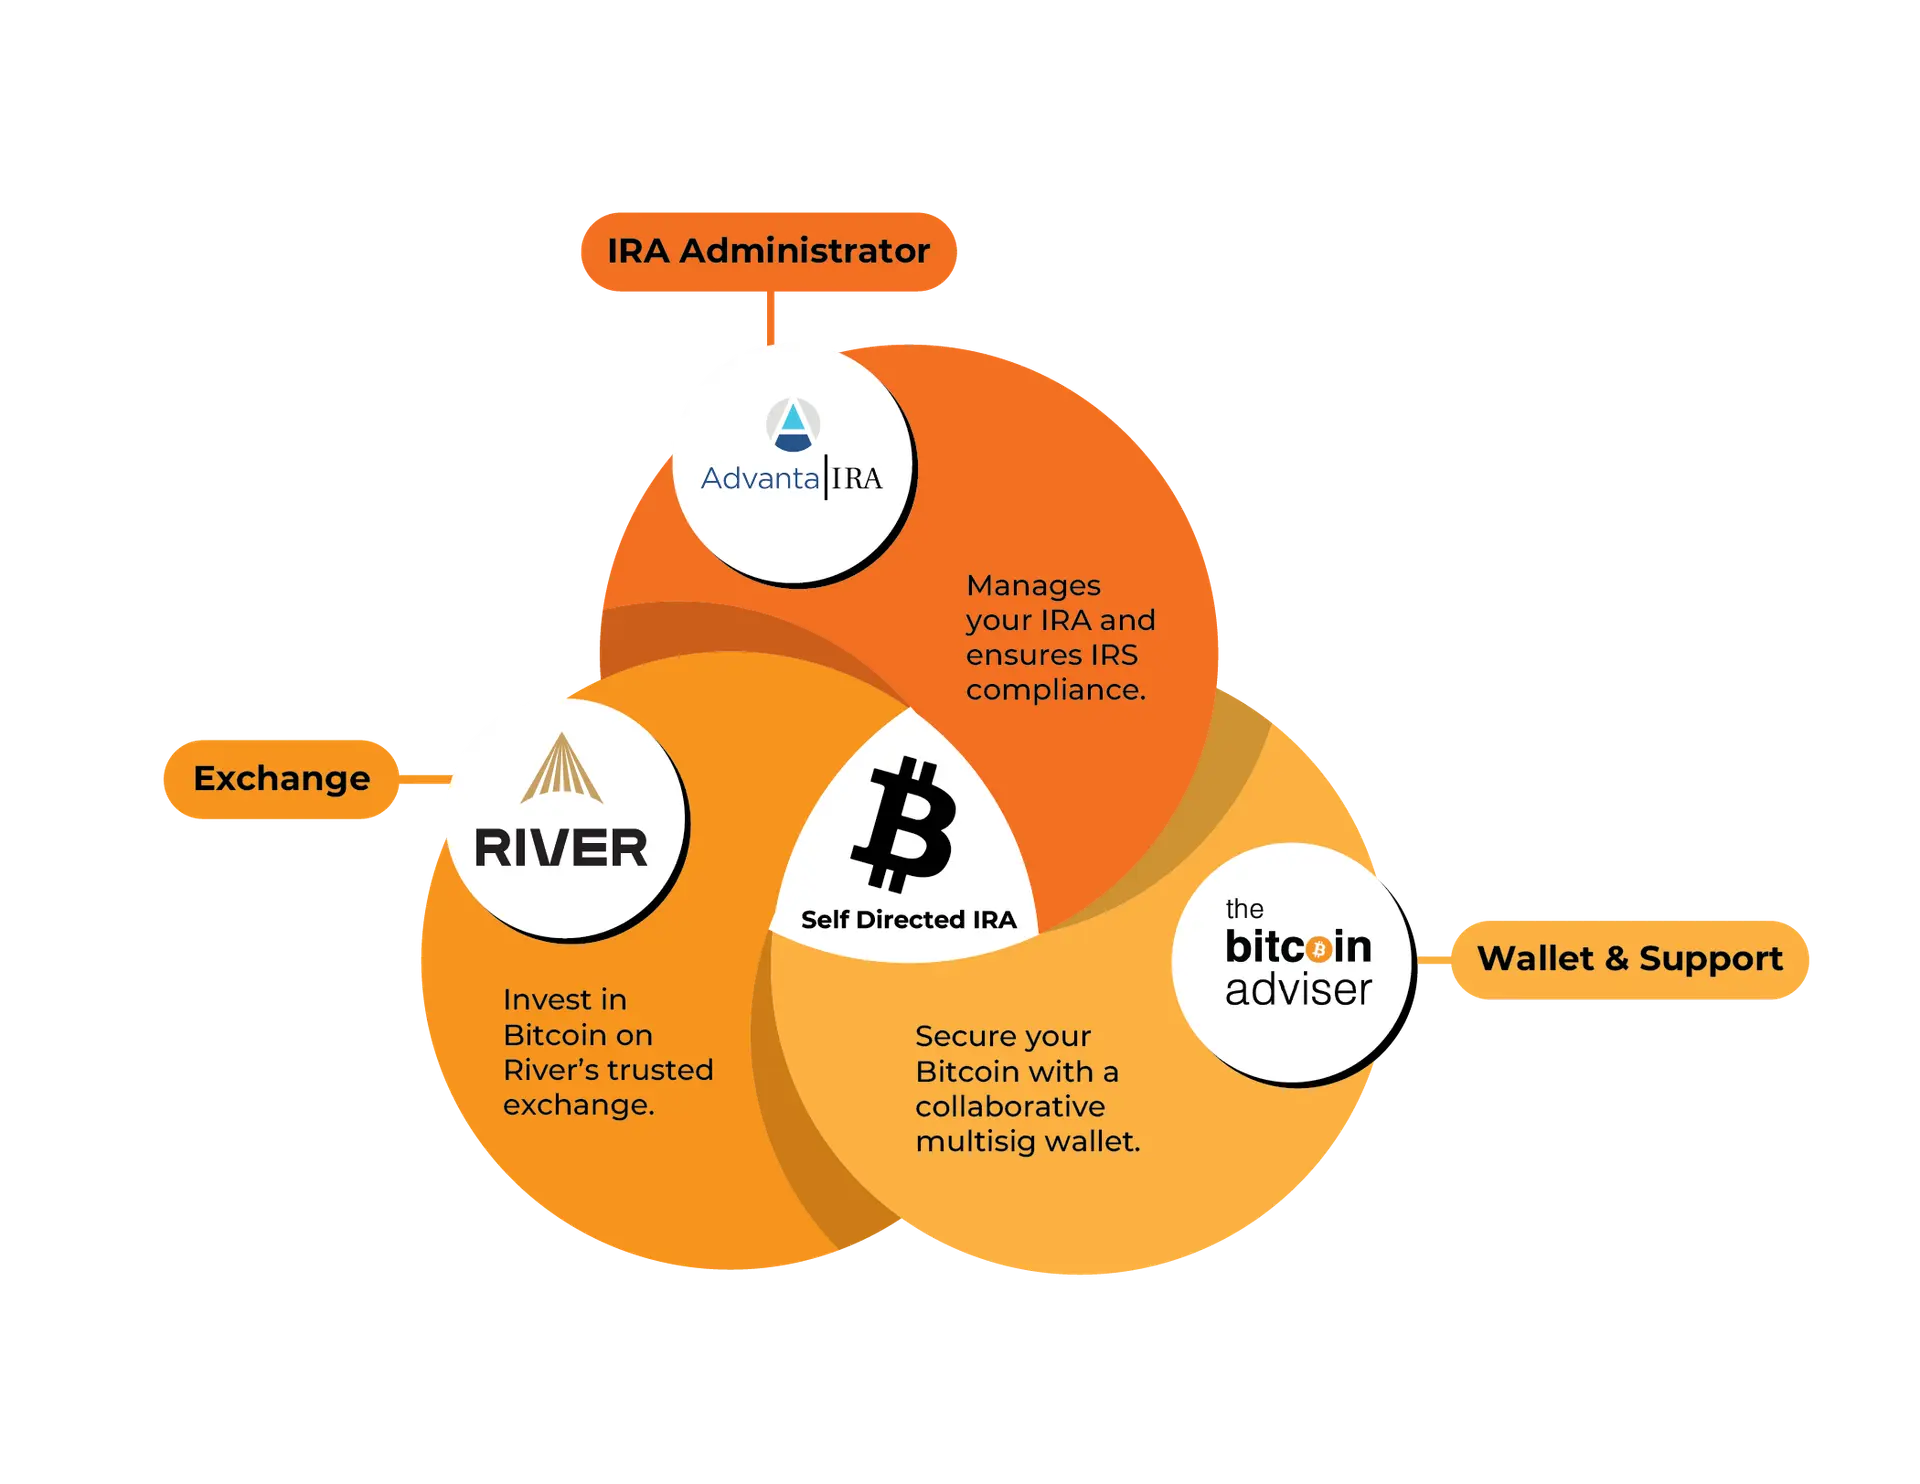
Holding Bitcoin in your IRA requires careful coordination across several critical components. At The Bitcoin Adviser, we partner with industry leaders to deliver an integrated and secure solution, while you work directly with Advanta Trust and your professional advisors on account decisions.
1. Work with Your IRA Custodian
Your IRA custodian is the IRS-authorized institution responsible for holding and managing your retirement assets. Advanta Trust is our partner—a specialized custodian that understands Bitcoin and offers support for Traditional, Roth, SEP, and Solo 401(k) IRAs.
You work directly with Advanta Trust to set up and manage your IRA. They ensure your IRA complies with IRS regulations. The Bitcoin Adviser does not act as your IRA custodian and does not provide financial, tax, legal, or investment advice.
2. Select a Trusted Exchange Partner
Acquiring Bitcoin for your IRA starts with the right exchange. We partner with River, a Bitcoin-only, publicly traded exchange that specializes in self-directed IRAs. River is critical because they:
- Allow third-party direct wire transfers from your IRA custodian
- Support “for the benefit of” accounts required for IRAs
- Pay interest on cash balances (approximately 3–3.5% paid in Bitcoin)
- Provide professional, high-touch customer service for retirement accounts
This account setup is critical to staying compliant with all IRS self-directed rules, ensuring you personally are not taking a distribution.
3. Secure Your Bitcoin with Collaborative Security
Self-custody is the cornerstone of owning Bitcoin in your IRA. The Bitcoin Adviser provides technical support to set up a multi-signature (multisig) vault where control is distributed among you, The Bitcoin Adviser, and a trusted third-party key holder. This eliminates single points of failure and helps protect your Bitcoin even in unforeseen circumstances.
You hold one key, maintaining direct access to your Bitcoin, while The Bitcoin Adviser and the third-party key holder hold additional keys, creating a robust security framework that can be paired with your custodian’s processes and IRS rules.
Why Choose The Bitcoin Adviser for Your Bitcoin IRA?
Navigating the world of Bitcoin IRAs can be complex. While many paths lead to Bitcoin exposure in an IRA, true control comes from holding actual Bitcoin in your self-custody vault. This approach combines tax-advantaged savings with the unmatched security and independence Bitcoin offers.
The Bitcoin Adviser provides technical support for self-custody Bitcoin in IRAs. We work alongside Advanta Trust (your IRA custodian) and River (your exchange partner) so that your IRA structure, acquisition of Bitcoin, and collaborative security setup all work together smoothly. You retain control of your keys; we never hold your Bitcoin or act as your IRA custodian.
Most “Bitcoin IRAs” give you exposure through custodial products or ETFs. Our clients focus on owning real Bitcoin in self-custody, with a structure designed for long-term security and inheritance.
True Self-Custody
Hold actual Bitcoin in your IRA, not Bitcoin-linked products. You maintain control of your keys while staying compliant with IRS regulations through your chosen custodian.
Collaborative Security
Multi-signature vault eliminates single points of failure. No one party can access your Bitcoin alone, including us.
Zero Losses Since 2016
Our track record speaks for itself. Since 2016, zero satoshis lost across all clients, including retirement accounts.
Estate Planning Ready
Built-in estate planning ensures your Bitcoin can transition seamlessly to beneficiaries through our Estate Plan Protocol.
Expert Technical Guidance
Scott Porter brings three decades of enterprise IT and security experience, specializing in self-directed IRAs and Advanta Trust coordination.
End-to-End Technical Support
We provide technical support for Bitcoin self-custody, wallet setup, and estate planning protocols, working alongside your IRA custodian and exchange partner to ensure secure operations.
Why Collaborative Security Matters
In today's uncertain world, security and resilience are more important than ever. Traditional pension systems, underfunded public plans, and fiat-based promises depend on demographics, taxation, and future political decisions. Bitcoin held in collaborative self-custody offers a different foundation—one that does not rely on future taxpayers or government solvency.
No Single Point of Failure
Even if one key is lost or compromised, your Bitcoin remains safe and accessible through the remaining keys.
Estate Planning Made Easy
In the event of your passing, your assets can transition seamlessly to your beneficiaries through our Estate Plan Protocol.
Enhanced Peace of Mind
With a multisig setup, your Bitcoin is shielded from loss, theft, or unauthorized access while maintaining your control.
IRA Integration & Compliance
Our technical framework is designed to work alongside your IRA custodian’s processes and IRS rules while preserving true ownership and control of your Bitcoin.
Bitcoin IRA Webinar: Complete Guide
Watch our comprehensive webinar with Advanta Trust, featuring Scott Porter and Peter Dunworth, as they discuss technical and operational aspects of holding Bitcoin in self-custody within retirement accounts. This is educational content only and does not constitute financial, tax, legal, or investment advice.
Key topics covered: Why Bitcoin in your IRA, the three-party setup (Advanta Trust, River, The Bitcoin Adviser), fees and costs, the 7-day waiting period, and answers to common questions.
Triple Tax Advantage: Your HSA, Your Bitcoin, Your Keys, Your Future
A Health Savings Account (HSA) isn't just for medical expenses—it's one of the most powerful tax-advantaged investment vehicles available. When you combine an HSA with Bitcoin self-custody, you unlock triple tax advantages while maintaining true ownership of your Bitcoin. The Bitcoin Adviser provides technical and operational support for self-custody Bitcoin in HSAs. We are not a financial services company and do not provide financial, tax, legal, or investment advice.
We work alongside trusted partners: Advanta Trust (your HSA custodian) and River (your exchange partner). Together, we help you set up and maintain self-custody Bitcoin in your HSA while you work directly with your HSA custodian and professional advisors on structure, suitability, and compliance.
Triple Tax Advantage Pre-tax, tax-free growth, tax-free withdrawals
Advanta Trust IRS-authorized HSA custodian
Who This Is For
This page is for U.S.-based individuals who want:
- Direct ownership of actual Bitcoin in their HSA (not just ETF exposure)
- A self-directed HSA with true self-custody of the asset
- To maximize the triple tax advantage while building long-term wealth
- Collaborative security and estate planning so HSA Bitcoin can be held for decades and passed on securely
You retain control of your keys. We never act as custodian or take possession of your Bitcoin.
The Triple Tax Advantage of HSAs
Health Savings Accounts offer a unique triple tax advantage that makes them one of the most powerful investment vehicles available—especially when combined with Bitcoin's growth potential.
Maximizing Your HSA: Many savvy HSA holders treat their account like a retirement account, paying medical expenses out-of-pocket when possible to allow their HSA investments to grow tax-free. For example, if you pay $300 out-of-pocket for a medical bill today, that same $300 left to grow in your HSA could be worth over $2,100 in 30 years, assuming a 7% annual return. With Bitcoin's historical growth potential, the compounding effect can be even more significant.
1. Pre-Tax Contributions Contributions are made before taxes are deducted from your paycheck, immediately reducing your taxable income. For 2025, contribution limits are $4,150 for individuals and $8,300 for families. If you're 55 or older, you can contribute an additional $1,000 per year.
2. Tax-Free Growth Unlike most investment accounts, all growth in your HSA—whether from interest, dividends, or capital gains—grows completely tax-free. This includes Bitcoin's potential appreciation.
3. Tax-Free Withdrawals When used for qualified medical expenses, withdrawals are completely tax-free. After age 65, you can withdraw for any reason (subject to ordinary income tax if not for medical expenses), making HSAs powerful retirement planning tools.
HSA Eligibility & Contribution Limits
To contribute to an HSA, you must be enrolled in a High Deductible Health Plan (HDHP). For 2025, an HDHP is defined as a health plan with a minimum deductible of $1,600 for individuals or $3,200 for families, and maximum out-of-pocket expenses of $8,050 for individuals or $16,100 for families.
2025 Contribution Limits
Individual: $4,150 per year
Family: $8,300 per year
Catch-up (55+): Additional $1,000 per year
Qualified Medical Expenses
Withdrawals for qualified medical expenses are tax-free. This includes doctor visits, prescriptions, dental care, vision care, and many other health-related expenses. Keep receipts—you can reimburse yourself years later.
After Age 65
Once you reach age 65, you can withdraw HSA funds for any reason. If not used for qualified medical expenses, withdrawals are subject to ordinary income tax (similar to a Traditional IRA), but no penalty applies.
No "Use It or Lose It"
Unlike Flexible Spending Accounts (FSAs), HSA funds roll over year to year and remain yours forever. There's no deadline to use the funds, making HSAs excellent long-term investment vehicles.
Why Choose The Bitcoin Adviser for Your Bitcoin HSA?
Most HSA providers limit you to traditional investments like stocks, bonds, or mutual funds. Some may offer Bitcoin ETFs, but these don't give you direct ownership. True control comes from holding actual Bitcoin in your self-custody vault. This approach combines the triple tax advantage of HSAs with the unmatched security and independence Bitcoin offers.
The Bitcoin Adviser provides technical support for self-custody Bitcoin in HSAs. We work alongside Advanta Trust (your HSA custodian) and River (your exchange partner) so that your HSA structure, acquisition of Bitcoin, and collaborative security setup all work together smoothly. You retain control of your keys; we never hold your Bitcoin or act as your HSA custodian.
For a deeper dive into HSAs and Bitcoin, see our comprehensive guide: "How to Hold Bitcoin in Your Health Savings Account (HSA)" by Scott Porter.
True Self-Custody
Hold actual Bitcoin in your HSA, not Bitcoin-linked products. You maintain control of your keys while staying compliant with IRS regulations through your chosen custodian.
Triple Tax Advantage
Pre-tax contributions, tax-free growth, and tax-free qualified withdrawals create one of the most powerful tax-advantaged structures available.
Zero Losses Since 2016
Our track record speaks for itself. Since 2016, zero satoshis lost across all clients, including HSA accounts.
Retirement Planning Power
After age 65, HSA funds can be withdrawn for any reason (subject to income tax if not for medical expenses), making your HSA a powerful retirement planning tool.
Expert Technical Guidance
Scott Porter brings three decades of enterprise IT and security experience, specializing in self-directed HSAs and Advanta Trust coordination.
How We Simplify Bitcoin HSA Custody
Holding Bitcoin in your HSA requires careful coordination across several critical components. At The Bitcoin Adviser, we partner with industry leaders to deliver an integrated and secure solution, while you work directly with Advanta Trust and your professional advisors on account decisions.
1. Work with Your HSA Custodian
Your HSA custodian is the IRS-authorized institution responsible for holding and managing your health savings account. Advanta Trust is our partner—a specialized custodian that understands Bitcoin and offers support for self-directed HSAs.
You work directly with Advanta Trust to set up and manage your HSA. They ensure your HSA complies with IRS regulations. The Bitcoin Adviser does not act as your HSA custodian and does not provide financial, tax, legal, or investment advice.
2. Select a Trusted Exchange Partner
Acquiring Bitcoin for your HSA starts with the right exchange. We partner with River, a Bitcoin-only, publicly traded exchange that specializes in self-directed retirement accounts. River is critical because they:
- Allow third-party direct wire transfers from your HSA custodian
- Support "for the benefit of" accounts required for HSAs
- Pay interest on cash balances (approximately 3–3.5% paid in Bitcoin)
- Provide professional, high-touch customer service for retirement accounts
This account setup is critical to staying compliant with all IRS self-directed rules, ensuring you personally are not taking a distribution.
3. Secure Your Bitcoin with Collaborative Security
Self-custody is the cornerstone of owning Bitcoin in your HSA. The Bitcoin Adviser provides technical support to set up a multi-signature (multisig) vault where control is distributed among you, The Bitcoin Adviser, and a trusted third-party key holder. This eliminates single points of failure and helps protect your Bitcoin even in unforeseen circumstances.
You hold one key, maintaining direct access to your Bitcoin, while The Bitcoin Adviser and the third-party key holder hold additional keys, creating a robust security framework that can be paired with your custodian's processes and IRS rules.
Why Collaborative Security Matters for Your HSA
HSAs are designed for long-term wealth building, especially when you pay medical expenses out-of-pocket and let your investments grow. Bitcoin held in collaborative self-custody offers a foundation that doesn't rely on traditional financial systems or third-party promises. This is particularly important for HSA holders who are building wealth over decades.
Estate Planning Made Easy
In the event of your passing, your HSA assets can transition seamlessly to your spouse (as beneficiary) or other beneficiaries through our Estate Plan Protocol.
HSA Integration & Compliance
Our technical framework is designed to work alongside your HSA custodian's processes and IRS rules while preserving true ownership and control of your Bitcoin.
Why Bitcoin in Your HSA
Educational information only—not financial, tax, legal, or investment advice. Based on decades of combined experience in finance, technology, and Bitcoin, here are perspectives on Bitcoin in HSAs from industry experts:
Triple Tax Advantage
HSAs offer the only triple tax advantage available: pre-tax contributions, tax-free growth, and tax-free qualified withdrawals. When combined with Bitcoin's growth potential, this creates a powerful wealth-building strategy.
Hedge Against Medical Inflation
Healthcare costs have historically risen faster than general inflation. Bitcoin's potential to preserve and grow purchasing power can help offset future medical expenses.
Retirement Planning Power
After age 65, HSA funds can be withdrawn for any reason, making your HSA a powerful retirement planning tool. Bitcoin's long-term growth potential can significantly enhance this benefit.
Generational Wealth Asset
For intergenerational wealth planning, Bitcoin in an HSA represents an opportunity to preserve and grow purchasing power across decades, especially when paired with robust estate planning protocols.
Model Your IRA Horizon
Before you coordinate with Advanta Trust and your tax advisers, explore illustrative year ranges for when Bitcoin in your IRA might support a target annual income. Adjust the inputs below to compare conservative, base, and aggressive growth scenarios. This does not model RMDs, Roth vs Traditional tax treatment, or custodian rules.
Live BTC reference price (USD): $81,512Updated live
In the base scenario, illustrative income could reach $80,000 a year (inflation adjusted: yes) in about 21 years.
Illustrative range across scenarios: 13 to 36 years. Not a guaranteed retirement date.
At the active scenario horizon: $5,219,815 portfolio (1.3920 BTC at modelled price $3,749,969).
Conservative
~36 years
12% illustrative CAGR
Base
~21 years
20% illustrative CAGR
Aggressive
~13 years
35% illustrative CAGR
What the model assumes
- Growth rates
- 12%, 20%, 35% a yearThe conservative, base and aggressive scenarios, selected by you for illustration. Not forecasts.
- Withdrawal rate
- 3% a yearIncome is the portfolio value times this rate.
- Inflation
- 3% a yearApplied to the income target, not to the portfolio.
- Values
- NominalAmounts are in USD at the modelled Bitcoin price.
- Contributions
- MonthlyEach month's contribution buys Bitcoin at that month's modelled price.
- Fees and tax
- None modelledNo fees, tax or account rules are deducted.
- Time limit
- 50 yearsHorizons beyond this are shown as beyond the cap.
- Reference price
- $81,512The starting Bitcoin price supplied for this run.
Educational only. Not financial, tax, legal, or investment advice. Horizon years are illustrative, not guaranteed retirement dates.
Key Insights from Our Experts
Educational information only—not financial, tax, legal, or investment advice. Based on decades of combined experience in finance, technology, and Bitcoin, here are perspectives on Bitcoin in retirement accounts from industry experts:
Important: Past performance is not a guarantee of future results. Bitcoin is a volatile asset and can experience large price swings and drawdowns. You should carefully consider your risk tolerance and consult with qualified advisors before making any investment decisions.
Best Performing Asset
Bitcoin has been one of the best-performing assets in the world over the past decade, including years returning many hundreds of percent in a single cycle.
Hedge Against Monetary Debasement
While the U.S. dollar and other fiat currencies are continually debased over time, Bitcoin has a fixed supply of 21 million coins, making it immune to monetary debasement and offering a potential long-term store of value.
No Counterparty Risk in Self-Custody
When held in self-custody, Bitcoin is a digital bearer asset with no direct counterparty risk. You're not relying on underfunded pension systems, bank solvency, or third-party promises to access your savings.
Institutional Adoption Ahead
This is the first time in history that individual investors can front-run major institutions and governments that are only beginning to hold Bitcoin as a strategic asset.
Generational Wealth Asset
For intergenerational wealth planning, Bitcoin represents an opportunity to preserve and grow purchasing power across decades, especially when paired with a tax-advantaged IRA structure and robust estate planning protocols.
Global, Ubiquitous Asset
Bitcoin is the first globally ubiquitous asset—the same everywhere in the world, available 24/7, and increasingly recognized as a strong form of collateral and long-term savings technology.
Common Questions About Bitcoin IRAs
Can I hold Bitcoin in any type of IRA?
Yes. With the right self-directed custodian, Bitcoin can be held in Traditional IRAs, Roth IRAs, SEP IRAs, and Solo 401(k)s. Your IRA custodian and your financial or tax advisor can help you decide which account type is appropriate for your situation. The Bitcoin Adviser provides technical support for self-custody once your IRA has been established.
Note: Health Savings Accounts (HSAs) also support Bitcoin self-custody and offer a unique triple tax advantage. See our dedicated Bitcoin HSA page for HSA-specific information.
What happens if I lose my key?
With our collaborative security model, losing one key does not mean losing access to your Bitcoin. The remaining keys can be used to regain control, ensuring your assets are always recoverable. This is one of the key advantages of multi-signature security.
How does this differ from Bitcoin ETFs in an IRA?
Bitcoin ETFs give you exposure to Bitcoin's price, but you don't own actual Bitcoin and you cannot self-custody the asset. With our approach, you hold real Bitcoin in self-custody, giving you true ownership, censorship resistance, and the ability to hedge against the traditional financial system. Learn more about why direct ownership matters →
What are the tax implications?
Generally, Bitcoin held in a Traditional IRA grows tax-deferred, and distributions are taxed as ordinary income. In a Roth IRA, qualified distributions are typically tax-free. The Bitcoin Adviser does not provide tax advice. You must consult with a qualified tax professional for guidance specific to your circumstances and the current IRS rules.
How long does the setup process take?
For new accounts, there is typically a 7-day waiting period (industry standard) from when your account opens before funds can be sent to purchase Bitcoin. Once that period passes, the process usually takes 2–4 weeks from initial consultation to Bitcoin in your vault. This includes opening or transferring your IRA, coordinating with Advanta Trust, setting up your River account, executing the Bitcoin purchase, and setting up your collaborative security vault.
What are the fees involved?
Advanta Trust fees: Typical fees include a $50 account opening fee, a $95 transaction fee per investment, a $295 annual record-keeping fee (for accounts over $15,000), plus wire fees (e.g., $15 incoming, $30 outgoing).
River exchange: Transaction fees apply based on River’s current fee schedule.
The Bitcoin Adviser: 1% annual fee paid in Bitcoin for self-custody assistance, estate planning protocols, and ongoing technical and operational support.
All third-party fees are subject to change. Please refer to Advanta Trust, River, and any other service providers for their current fee schedules and terms.
Is there a minimum investment amount?
There is no specific minimum investment amount required by The Bitcoin Adviser. Your IRA custodian may have its own policies, and standard IRS contribution limits apply to new contributions. For rollovers or transfers from existing retirement accounts, minimums are typically defined by the sending or receiving custodians. Speak with your IRA custodian and tax advisor for details on limits and suitability.
Can I transfer existing personal Bitcoin into my IRA?
No. You can only make cash contributions to an IRA. Additionally, you cannot sell personal Bitcoin to your IRA (this is treated as a prohibited transaction). If you have Bitcoin in another retirement account, you would need to convert it to cash, transfer the cash, and then repurchase Bitcoin in the new account—this is generally not a taxable event for an IRA-to-IRA transfer, but you must confirm details with your custodian and tax advisor.
Do I need an LLC for this setup?
No. For Bitcoin-only investments, direct investment through your IRA custodian is usually the simplest and most straightforward approach. LLC checkbook control is available if you and your advisors decide to diversify into multiple asset types (Bitcoin, real estate, etc.), but it is not required for Bitcoin-only IRAs.
Can I have multiple vaults in one wallet platform?
Yes. You can have multiple vaults in one wallet platform—one for your IRA Bitcoin, one for personal Bitcoin, one for HSA Bitcoin, etc. Each vault is separate and never co-mingled, but can be managed through the same secure platform with collaborative security.
Common Questions About Bitcoin HSAs
What makes HSAs different from IRAs?
HSAs offer a unique triple tax advantage: pre-tax contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. IRAs offer tax-deferred or tax-free growth, but contributions are either pre-tax (Traditional) or after-tax (Roth). HSAs also have no "use it or lose it" rule—funds roll over indefinitely. After age 65, HSA funds can be withdrawn for any reason (subject to income tax if not for medical expenses), making them powerful retirement planning tools. For more on Bitcoin IRAs, see our Bitcoin IRA page.
Do I need a High Deductible Health Plan (HDHP) to have an HSA?
Yes. To contribute to an HSA, you must be enrolled in an HDHP. For 2025, an HDHP requires a minimum deductible of $1,600 for individuals or $3,200 for families. You cannot contribute to an HSA if you have other health coverage (with some exceptions, such as dental, vision, or disability insurance). Consult with your health insurance provider and tax advisor to confirm your eligibility.
Can I use my HSA for non-medical expenses?
Before age 65, withdrawals for non-qualified medical expenses are subject to ordinary income tax plus a 20% penalty. After age 65, you can withdraw HSA funds for any reason—if not used for qualified medical expenses, withdrawals are subject to ordinary income tax (similar to a Traditional IRA), but no penalty applies. This makes HSAs powerful retirement planning tools.
How does this differ from Bitcoin ETFs in an HSA?
Bitcoin ETFs give you exposure to Bitcoin's price, but you don't own actual Bitcoin and you cannot self-custody the asset. With our approach, you hold real Bitcoin in self-custody, giving you true ownership, censorship resistance, and the ability to hedge against the traditional financial system. Learn more about why direct ownership matters →
What are the tax implications of Bitcoin in an HSA?
Bitcoin held in an HSA grows tax-free, and withdrawals for qualified medical expenses are tax-free. After age 65, withdrawals for non-medical expenses are subject to ordinary income tax. The Bitcoin Adviser does not provide tax advice. You must consult with a qualified tax professional for guidance specific to your circumstances and the current IRS rules.
How long does the setup process take?
For new accounts, there is typically a 7-day waiting period (industry standard) from when your account opens before funds can be sent to purchase Bitcoin. Once that period passes, the process usually takes 2–4 weeks from initial consultation to Bitcoin in your vault. This includes opening or transferring your HSA, coordinating with Advanta Trust, setting up your River account, executing the Bitcoin purchase, and setting up your collaborative security vault.
What are the fees involved?
Advanta Trust fees: Typical fees include a $50 account opening fee, a $95 transaction fee per investment, a $295 annual record-keeping fee (for accounts over $15,000), plus wire fees (e.g., $15 incoming, $30 outgoing).
River exchange: Transaction fees apply based on River's current fee schedule.
The Bitcoin Adviser: 1% annual fee paid in Bitcoin for self-custody assistance, estate planning protocols, and ongoing technical and operational support.
All third-party fees are subject to change. Please refer to Advanta Trust, River, and any other service providers for their current fee schedules and terms.
Can I have multiple vaults in one wallet platform?
Yes. You can have multiple vaults in one wallet platform—one for your HSA Bitcoin, one for personal Bitcoin, one for IRA Bitcoin, etc. Each vault is separate and never co-mingled, but can be managed through the same secure platform with collaborative security.
You work directly with Advanta Trust (or another qualified IRA custodian) to establish and manage your IRA. For scope, risks, and our alignment with US frameworks, see Scope & Risks and Authority & Standards (US).
You work directly with Advanta Trust (or another qualified HSA custodian) to establish and manage your HSA. For scope, risks, and our alignment with US frameworks, see Scope & Risks and Authority & Standards (US).
Get Started
Take the First Step Toward Securing Your Future
Whether you're ready to roll over an existing IRA into Bitcoin or exploring options for the first time, The Bitcoin Adviser provides technical support for self-custody Bitcoin in IRAs. We do not provide financial, tax, legal, or investment advice. Schedule a call today to learn about our technical support services for Bitcoin self-custody in retirement accounts, and speak with your professional advisors about whether this strategy is appropriate for you.